Curve Selected Yields & Key Metrics: Week 41, 2026
Selected yields and key metrics as of the 8th October, 2026.
Curve this week in 60 seconds
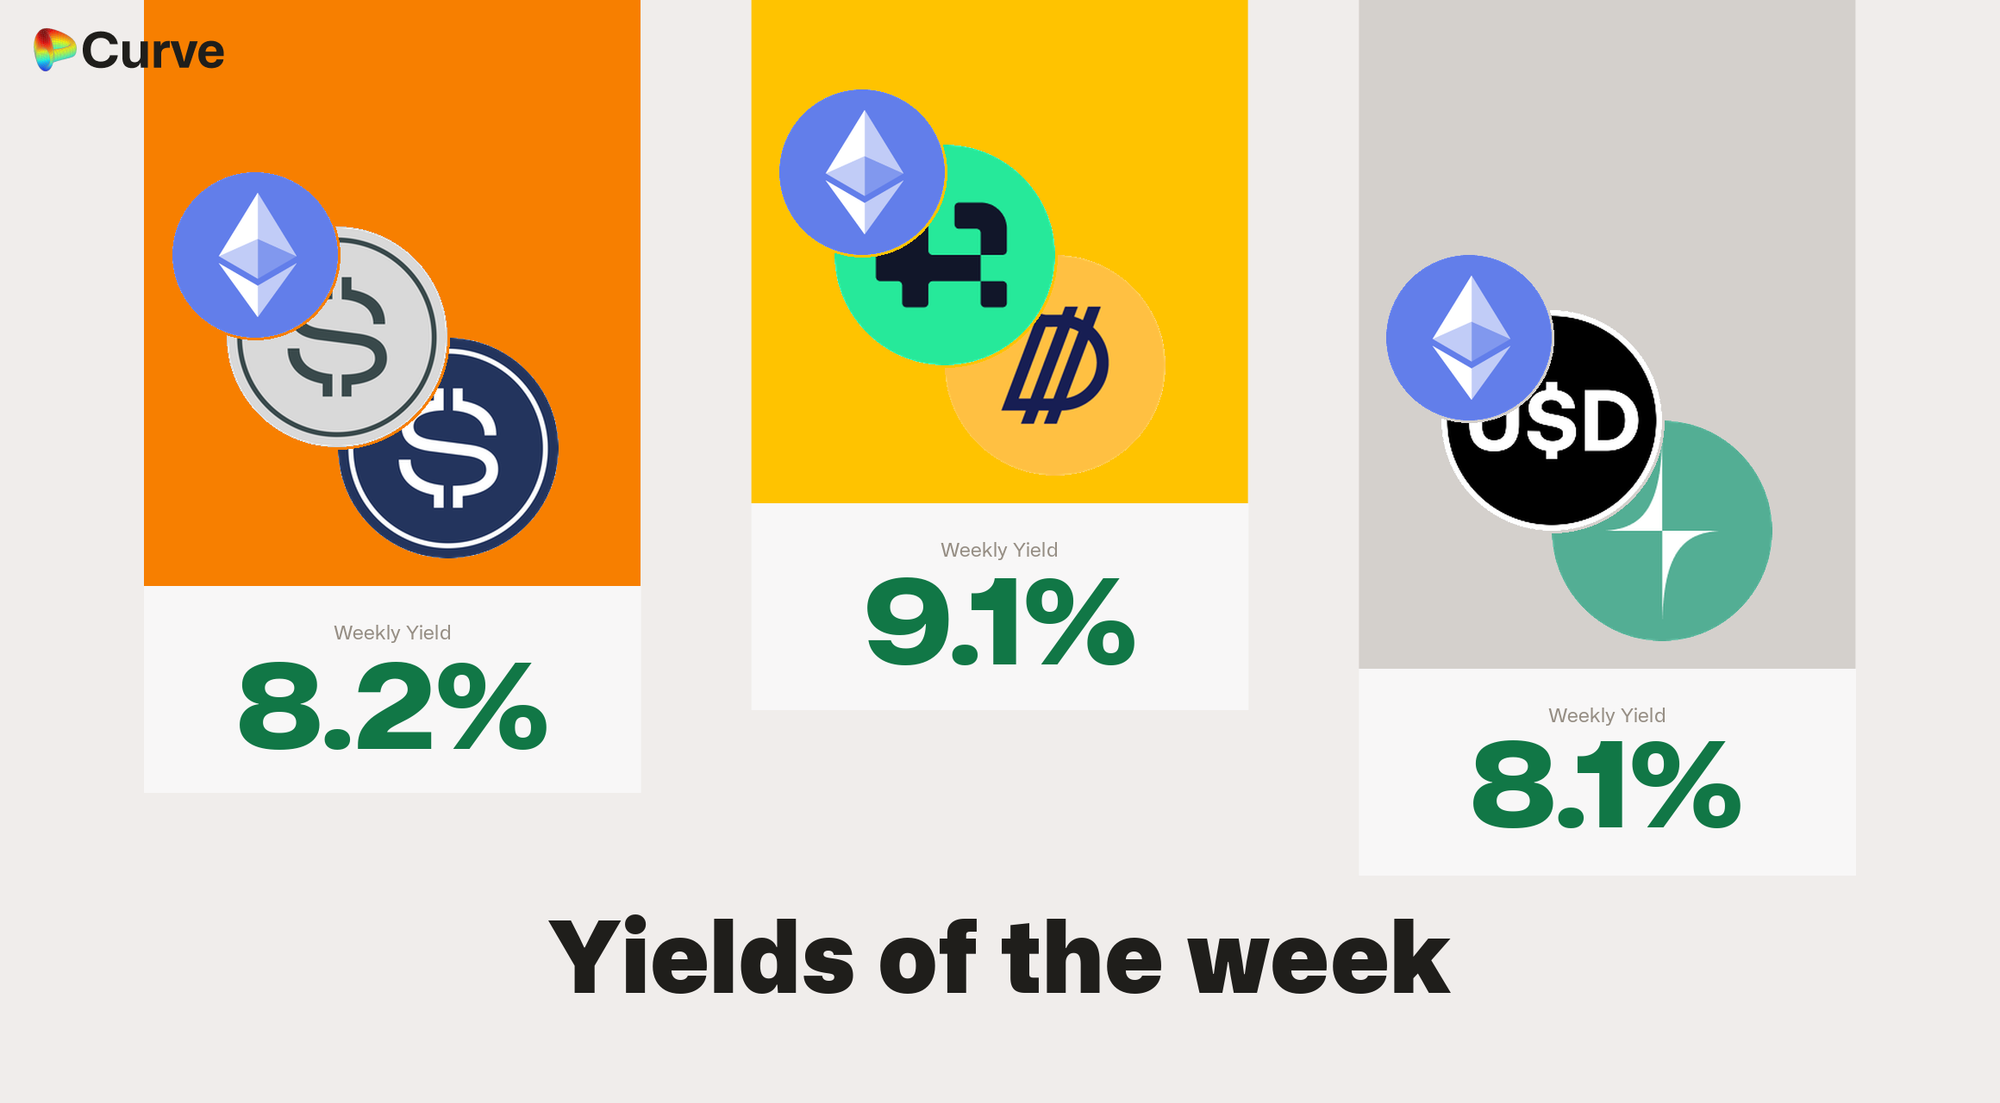
- USD LP highlights: reUSD (Resupply)/sDOLA 9.1% and sUSDx (Axis)/USDx (Axis) 8.2% modeled APR.
- Lending: supply crvUSD against sUSDe 5.4% APR; against sDOLA 5.2%.
- ETH LP highlights: ETH/ETHx 5.5% modeled APR.
- Tripool: crvUSD/WETH/CRV 6.0% modeled APR, combining dollar, ETH and CRV exposure.
- Coming next: LP-backed Llamalend borrowing is up for approval, opening a route to reUSD (Resupply)/sfrxUSD LP loops if the vote passes.
Selected yields
Markets shown have at least $100,000 in pool liquidity or supplied assets. Pool APRs model a new $100,000 deposit using seven-day LP growth and current unboosted rewards at unchanged income. Actual rates are variable; these are selected candidates, not a global top-yield or risk ranking. CRV rewards can be boosted via Convex, StakeDAO or Yearn. StableSwap pools with more than 85% of value or normalized reserves in one coin are omitted. FXSwap pools, such as zCHF/crvUSD, are assessed separately from this stablecoin-parity cutoff.
Selected USD yields
| Chain | Market | APR |
|---|---|---|
 |  reUSD (Resupply)  sDOLA | 9.1% |
|  sUSDx (Axis)  USDx (Axis) | 8.2% |
|  frxUSD  USG | 8.1% |
| reUSD (Resupply) scrvUSD | 8.0% |
|  USDC USG | 7.8% |
| USG sDOLA | 7.8% |
| frxUSD  sUSDai | 7.6% |
| reUSD (Resupply) sfrxUSD | 7.3% |
| reUSD (Resupply) fxUSD | 6.8% |
| frxUSD trUSD | 6.5% |
| scrvUSD  sUSDe | 6.4% |
|  crvUSD sUSDe | 5.7% |
Selected Llamalend supply yields
| Chain | Lent asset | Collateral | APR |
|---|---|---|---|
| crvUSD | sUSDe | 5.4% |
| crvUSD | sDOLA | 5.2% |
| crvUSD | sfrxUSD | 5.1% |
| crvUSD |  wstETH | 4.8% |
| crvUSD |  syrupUSDC | 4.4% |
| crvUSD |  svZCHF | 3.8% |
| crvUSD |  sreUSD (Resupply) | 3.5% |
Lending APR may include borrower interest and CRV rewards. Supplier exposure includes the borrower collateral shown, and withdrawal liquidity varies with utilization.
Selected BTC and ETH yields
| Chain | Market | Asset | APR |
|---|---|---|---|
|  ETH  ETHx | ETH | 5.5% |
|  ETH+  WETH | ETH | 3.5% |
| WETH weETH | ETH | 2.5% |
|  WBTC  cbBTC  hemiBTC | BTC | 2.5% |
|  tETH weETH | ETH | 2.3% |
|  stETH  frxETH | ETH | 1.9% |
Other selected yields
| Chain | Market | Asset | APR |
|---|---|---|---|
| crvUSD WETH CRV | TRICRYPTO | 6.0% |
| crvUSD  ZCHF | FXSwap | 4.7% |
|  GHO cbBTC WETH | TRICRYPTO | 4.6% |
| USDC WBTC WETH | TRICRYPTO | 2.7% |
|  USDT WBTC WETH | TRICRYPTO | 1.9% |
Protocol activity and stability
crvUSD & scrvUSD
| Metric | Value | Vs W40 |
|---|---|---|
| Mint-market debt | $74.8M | +1.1% |
 scrvUSD yield (APY) | 2.9% | -0.3 pp |
| scrvUSD assets / mint debt | 21.2% | -0.9 pp |
| crvUSD oracle price | $0.9998 | $0.0000 |
| Average borrow APY | 3.6% | -0.1 pp |
| PegKeeper debt | 20.58M crvUSD | -13.17M crvUSD |
| Mint borrowing fees collected | $50.2k | -6.7% |
Changes compare with last week’s publication. Stocks use 08:00 UTC in both issues; fees cover completed Thursday-to-Thursday weeks. Average borrow APY is debt-weighted. PegKeeper debt is minted pool liquidity, not a loss reserve.
Llamalend
| Metric | Value | Vs W40 |
|---|---|---|
Llamalend TVL | $269M | -0.6% |
Supplied | $97M | +1.3% |
Borrowed | $151M | +2.5% |
Collateral | $247M | 0.0% |
Loans | 1,208 | +8 |
V2 accrued admin fees | $2.1k | +14.8% |
TVL counts lending and mint markets; supplied assets are lending-only.
One borrower used the leverage route to borrow about 646,000 crvUSD and buy roughly 532,000 sfrxUSD in the old v1 market. Separately, another borrowed 580,000 crvUSD against 572,169 syrupUSDC.
DAO
| Metric | Value | Vs W40 |
|---|---|---|
 veCRV distribution | $111.1k | +18.1% |
| veCRV APR | 1.915% | +0.287 pp |
| CRV emissions (weekly gauge allocation) | 1.86M CRV ($727.9k) | 0.00% |
| Annual CRV inflation | 4.008% | -0.003 pp |
Weekly CRV emissions are scheduled gauge allocations, not tokens already claimed. Their change is measured in CRV, not dollars.
Governance and protocol updates
First LP-backed Llamalend market up for approval
Vote 1501 would activate a v2 market for reUSD (Resupply)/sfrxUSD LP collateral with an initial 3M crvUSD borrowing cap. LP holders could borrow crvUSD without unwinding their position, while pool fees and sfrxUSD yield continue to accrue.
Loopers could use borrowed crvUSD to add more LP collateral. Compare LP returns and any future incentives with borrowing and execution costs before levering up. Voting closes next Thursday; launch still requires passage and execution.
Gauge cleanup and v2 migration
The DAO completed a cleanup of outdated gauges: vote 1499 ended CRV emissions for the old CRV/cvxCRV pool and old sfrxUSD/crvUSD v1 vault. Their pools and loans remain open. Users in the legacy sfrxUSD market should move to the v2 market when feasible.
New alUSD/avUSD liquidity route
Vote 1500 would make the alUSD/avUSD pool eligible for future CRV incentives to help build liquidity between Alchemix and Avant. It adds a direct swap route for alUSD holders and an Ethereum venue for bridged avUSD. The pool is still at seed liquidity; rewards require approval, execution and subsequent gauge-weight votes.
App improvements
The pools page now has a Residual rewards tab for finding unclaimed rewards from former LP positions. veCRV holders can also claim their fee rewards from the Lock CRV tab.
veCRV vote incentives
Existing veCRV holders can compare two campaigns on Votemarket’s direct-veCRV ballot: alETH/frxETH offers a 900 ALCX period budget, while HemiBTC/cbBTC/WBTC offers 1,850.74 USDC.
Both campaigns are open to all voters and cap rewards per veCRV. Budgets are shared voter incentives, not LP APR. Check the ten-day gauge-vote cooldown and voting/claim costs before reallocating.
Ecosystem news
Borrowing dollars against Swiss-franc savings
A new Curve explainer shows how svZCHF holders can borrow crvUSD without selling their Swiss-franc savings. The collateral keeps earning its native savings yield, while the ZCHF/crvUSD FXSwap pool supplies pricing and the conversion route used during liquidation protection.
Explore Curve
Explore Curve pools, Llamalend markets or savings crvUSD. Choose the product that fits the asset and liquidity you need.
Risk information: pool risks, lending risks and crvUSD risks.