Curve Selected Yields & Key Metrics: Week 40, 2026
Selected yields and key metrics as of the 1st October, 2026.
Curve this week in 60 seconds
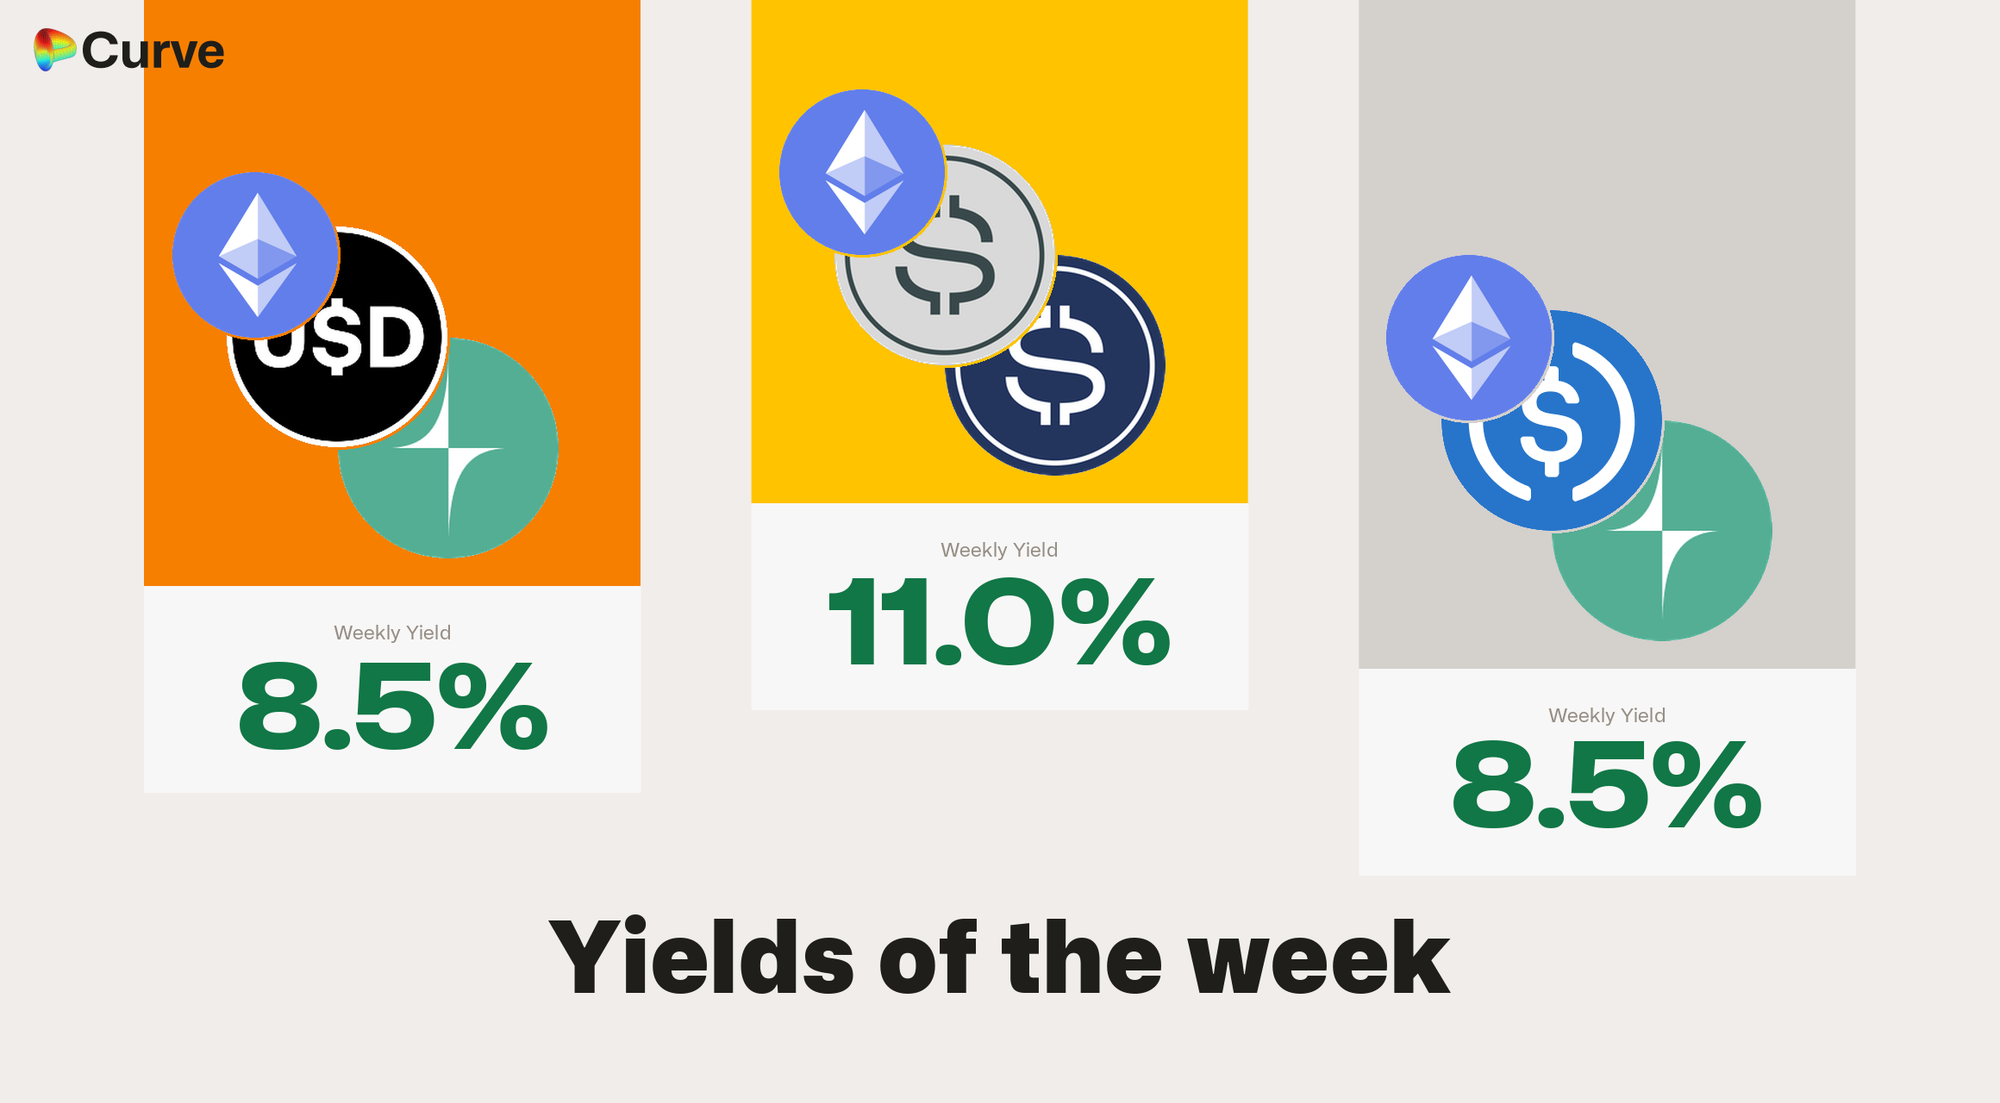
- USD LP highlights: sUSDx (Axis)/USDx (Axis) 11.0% and frxUSD (Frax)/USG (Tangent) 8.5% modeled APR.
- Lending: supply crvUSD against sfrxUSD 4.8% APR; against wstETH 9.3%.
- ETH LP highlights: ETH/ETHx (Stader) 6.3% modeled APR, with ETH price and staking-token risk.
- Tripool: crvUSD (Curve)/WETH/CRV (Curve) 6.2% modeled APR, combining dollar, ETH and CRV exposure.
sUSDx/USDx’s estimate comes from LP growth rather than CRV rewards; frxUSD/USG’s depends mostly on CRV incentives. Check the return source and receipt-redemption terms, not just the headline APR.
Selected yields
Markets shown have at least $100,000 in pool liquidity or supplied assets. Pool APRs model a new $100,000 deposit using seven-day LP growth and current unboosted rewards at unchanged income. Actual rates are variable; these are selected candidates, not a global top-yield or risk ranking. CRV rewards can be boosted via Convex, StakeDAO or Yearn. StableSwap pools with more than 75% of value or normalized reserves in one coin are omitted.
Selected USD yields


sUSDai holds loan exposure with 30-day unstaking epochs. USDx has synthetic-dollar backing and counterparty risk. The frxUSD/sUSDai estimate no longer includes the WFRAX or CHIP reward components present in last week’s snapshot.
Selected Llamalend supply yields
| Chain | Lent asset | Collateral | APR |
|---|---|---|---|
 |  crvUSD |  wstETH | 9.3% |
| crvUSD |  svZCHF | 4.8% |
| crvUSD |  sfrxUSD | 4.8% |
| crvUSD |  sDOLA | 4.8% |
| crvUSD |  syrupUSDC | 4.4% |
| crvUSD |  sUSDe | 3.8% |
| crvUSD |  fxSAVE | 3.5% |
| crvUSD |  sreUSD | 3.0% |
Lending APR may include borrower interest and CRV rewards. Supplier exposure includes the borrower collateral shown, and withdrawal liquidity varies with utilization.
Selected BTC and ETH yields
| Chain | Market | Asset | APR |
|---|---|---|---|
|  ETH  ETHx (Stader) | ETH | 6.3% |
|  ETH+ (Reserve)  WETH | ETH | 4.4% |
|  WBTC (BitGo)  cbBTC (Coinbase)  hemiBTC (Hemi) | BTC | 2.5% |
|  tETH (Treehouse)  weETH (ether.fi) | ETH | 2.4% |
|  stETH (Lido)  frxETH (Frax) | ETH | 1.8% |
Other selected yields
| Chain | Market | Asset | APR |
|---|---|---|---|
| crvUSD (Curve)WETH CRV (Curve) | TRICRYPTO | 6.2% |
| crvUSD (Curve) ZCHF (Frankencoin) | FOREX | 5.1% |
|  GHO (Aave)cbBTC (Coinbase)WETH | TRICRYPTO | 4.6% |
|  USDC (Circle)WBTC (BitGo)WETH | TRICRYPTO | 3.0% |
|  USDT (Tether)WBTC (BitGo)WETH | TRICRYPTO | 2.1% |
Protocol activity and stability
crvUSD & scrvUSD
| Metric | Value | Vs W39 |
|---|---|---|
| Mint-market debt | $74.0M | -4.4% |
 scrvUSD yield (APY) | 3.2% | -0.1 pp |
| scrvUSD assets / mint debt | 22.0% | +1.3 pp |
| crvUSD oracle price | $0.9999 | $0.0000 |
| Average borrow APY | 3.7% | 0.0 pp |
| PegKeeper debt | 33.75M crvUSD | +11.05M crvUSD |
| Mint borrowing fees collected | $53.9k | +3.2% |
Changes compare with last week’s publication: stocks use 08:00 UTC this week versus 12:00 UTC last week; fees cover completed Thursday-to-Thursday weeks. Average borrow APY is debt-weighted. PegKeeper debt is minted pool liquidity, not a loss reserve.
Repayments by two WBTC-backed borrowers exceeded the net mint-debt decline: one repaid about $2.39M and another about $1.84M.
Llamalend
| Metric | Value | Vs W39 |
|---|---|---|
Llamalend TVL | $271M | -0.6% |
Supplied | $96M | +2.0% |
Borrowed | $147M | -0.6% |
Collateral | $247M | -0.4% |
Loans | 1,200 | +22 |
V2 accrued admin fees | $1.8k | +8.6% |
TVL counts lending and mint markets; supplied assets are lending-only.
A borrower closed roughly $532k of debt in the old sfrxUSD market, then separately borrowed 565,000 crvUSD to add sDOLA exposure.
DAO
| Metric | Value | Vs W39 |
|---|---|---|
 veCRV distribution | $94.0k | -19.1% |
| veCRV APR | 1.628% | -0.729 pp |
| CRV emissions (weekly gauge allocation) | 1.86M CRV ($721.6k) | +1.56% |
| Annual CRV inflation | 4.011% | -0.003 pp |
Weekly CRV emissions are scheduled gauge allocations, not tokens already claimed. Their change is measured in CRV, not dollars. The source revised the prior gauge allocation after last week’s publication, so that comparison includes a data revision.
Governance and protocol updates
App improvements
veCRV fee claiming has moved into the DAO’s CRV locker page. Supported Llamalend leverage routes now use market-specific slippage defaults and external-router fees.
Vote would end incentives for two old gauges
Ownership vote 1499 would stop future CRV emissions to the old CRV/cvxCRV pool and old sfrxUSD/crvUSD v1 vault, reducing rewards for existing users. It would not close the pool or loans; the newer sfrxUSD Llamalend lending market in this issue is a different one.
veCRV vote incentives
Existing veCRV holders can compare two live campaigns on Votemarket’s veCRV ballot: DOLA/sUSDe has a 40,000 DOLA period budget, and OETH/WETH has 10,000 USDC.
These budgets are shared among eligible voters, not LP APR. Check campaign caps, the ten-day gauge-vote cooldown and voting/claim costs before reallocating.
Explore Curve
Explore Curve pools, Llamalend markets or savings crvUSD. Choose the product that fits the asset and liquidity you need.
Risk information: pool risks, lending risks and crvUSD risks.