Curve Best Yields & Key Metrics: Week 38, 2026
Best yields and key metrics as of the 17th September, 2026.
Curve this week in 60 seconds
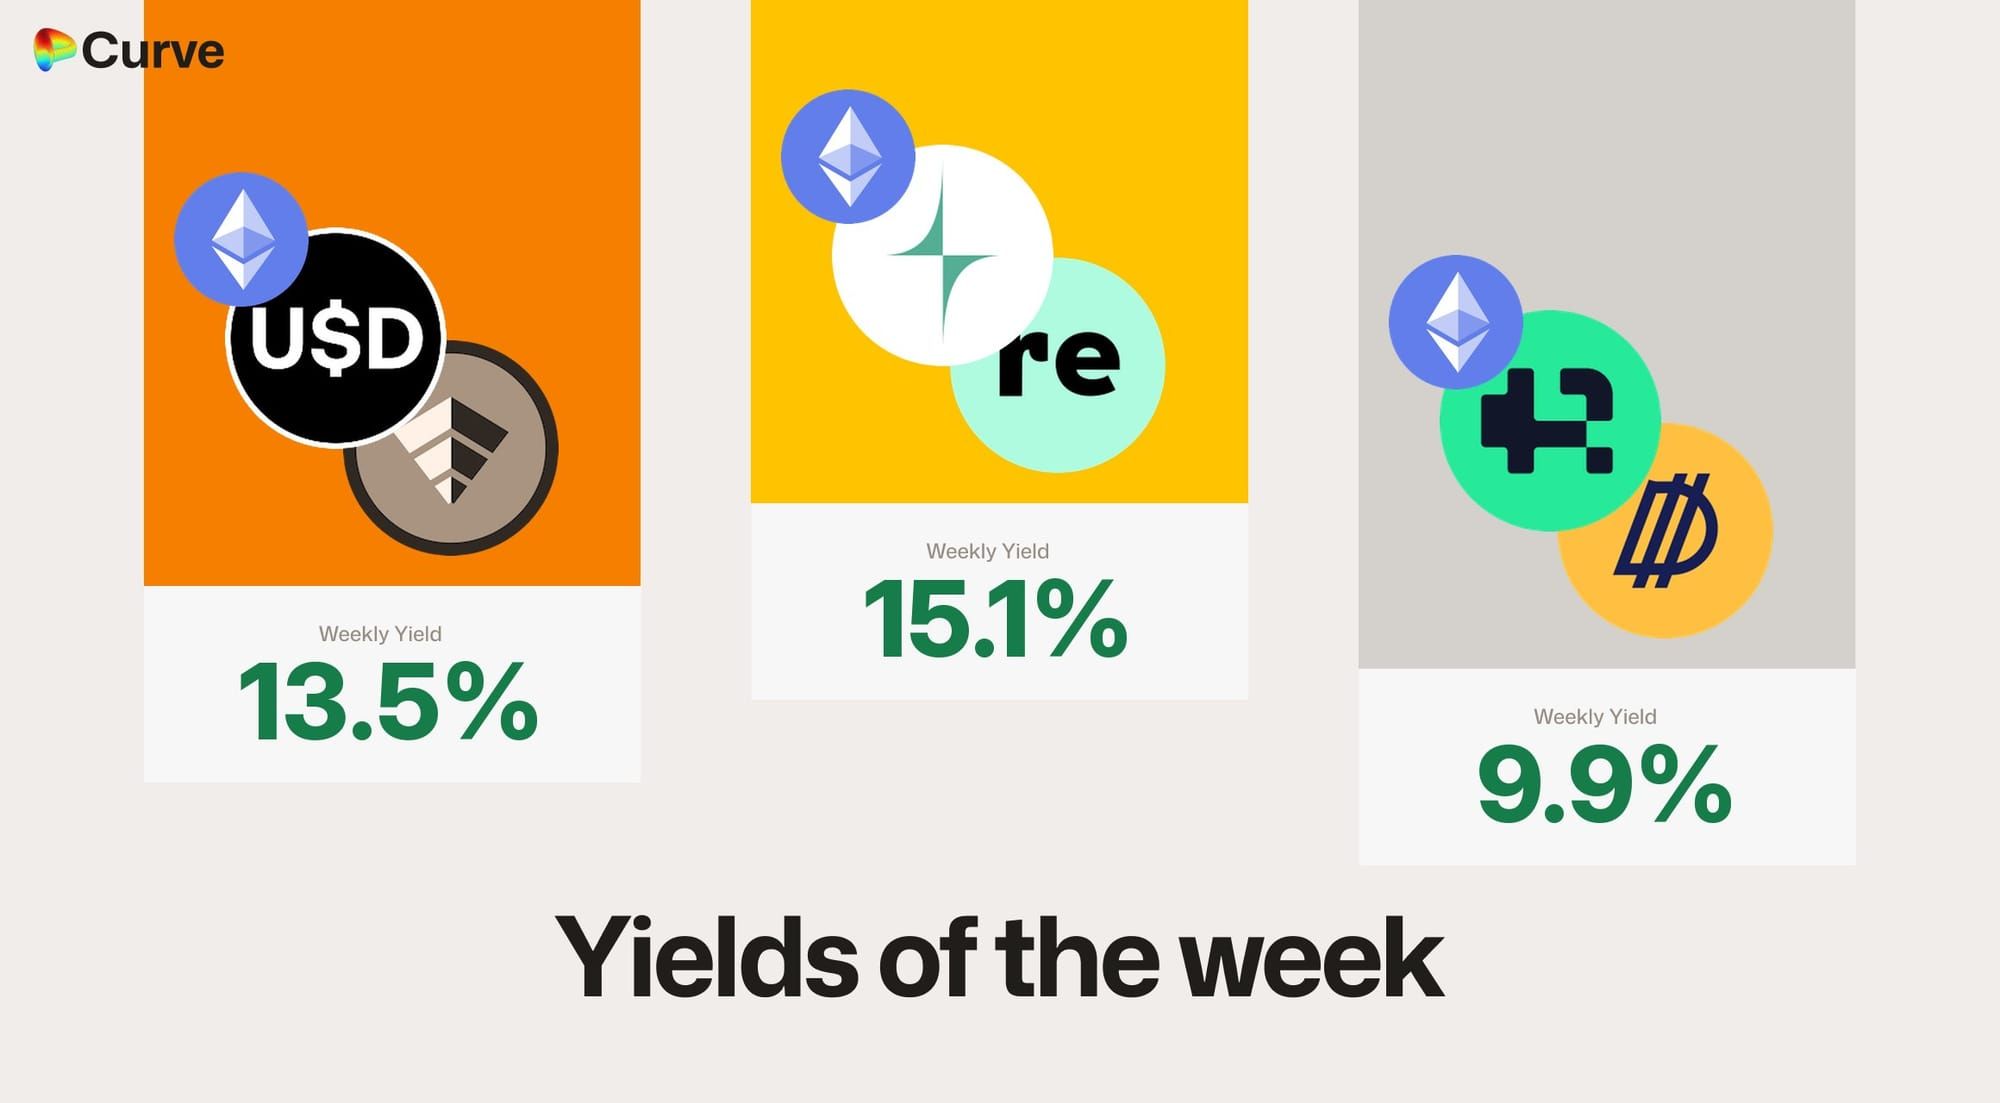
- USD pool yields: sUSG/reUSD (Re Protocol) at 15.1%, frxUSD/sUSDai at 13.5% and reUSD (Resupply)/sDOLA at 9.9% estimated APR.
- Lending: compare crvUSD against svZCHF collateral and crvUSD against syrupUSDC collateral.
- crvUSD: average borrowing APY was 3.6% at Thursday noon, up 1.0 pp week on week. Mint-market debt has since risen to $77.8M.
- BTC and ETH: compare ETH+/WETH and cbBTC/WBTC for crypto-denominated exposure rather than dollar exposure.
- CRV holders: compare CRV/cvxCRV pool yield with the separate voting-reward opportunities for existing veCRV holders. These require different positions.
- Ecosystem: Metronome says its backing shortfall is closed and its internal swap remains closed. Its synths still trade below par.
Choose the exposure first: compare USD pools with USD pools, BTC/ETH pools with similar assets, and lending markets by borrower collateral. Then check the source of yield and the liquidity available to exit.
Selected yields
Selected markets have at least $100,000 in pool liquidity or supplied assets; these are not an exhaustive ranking of every Curve opportunity. Estimated APRs use a modeled $100,000 deposit, trailing seven-day LP growth and current unboosted rewards where applicable. The dilution estimate assumes unchanged income; it is not a quote or a guaranteed return.
Selected USD yields
| Chain | Market | APR |
|---|---|---|
 |  sUSG  reUSD (Re Protocol) | 15.1% |
|  frxUSD  sUSDai | 13.5% |
|  reUSD (Resupply)  sDOLA | 9.9% |
|  sUSDx  USDx | 9.6% |
 |  frxUSD  FXB20551231 | 9.3% |
| frxUSD USD3 | 8.3% |
| reUSD (Resupply) scrvUSD | 8.0% |
| reUSD (Resupply) sfrxUSD | 7.5% |
|  USGsDOLA | 6.9% |
| scrvUSDsDOLA | 6.5% |
Re Protocol's reUSD and Resupply USD are unrelated assets. Resupply reUSD was priced at about $0.989 in the checked data. Their issuer, collateral and redemption risks differ; token losses can outweigh yield. frxUSD/sUSDai includes CHIP rewards, whose value can change.
Top Llamalend supply yields
| Chain | Lent asset | Collateral | APR |
|---|---|---|---|
|  crvUSD |  svZCHF | 6.2% |
 |  USDC |  wstETH | 6.0% |
| crvUSD |  syrupUSDC | 4.8% |
| crvUSD | sfrxUSD (v2) | 4.3% |
| crvUSD | sDOLA | 4.0% |
| crvUSD |  sUSDe | 3.9% |
| crvUSD |  wstETH | 3.1% |
| crvUSD | sfrxUSD (v1) | 2.9% |
| crvUSD |  sreUSD | 2.7% |
| USDC |  WBTC | 2.5% |
Supply returns can include borrower interest and CRV rewards. Markets with any reported bad debt are excluded. Check the live rate and available withdrawal liquidity before supplying.
Selected BTC and ETH yields
| Chain | Market | Asset | APR |
|---|---|---|---|
|  ETH+  WETH | ETH | 6.3% |
|  cbBTC  WBTC | BTC | 3.5% |
|  ETH  ETHx | ETH | 3.0% |
| WBTCcbBTC hemiBTC | BTC | 2.5% |
 |  cbBTC  WBTC  LBTC | BTC | 2.4% |
|  tETH  weETH | ETH | 2.2% |
BTC and ETH pools retain exposure to crypto prices and add token-issuer and relative-price risks; a quoted APR does not protect their dollar value.
Other selected yields
| Chain | Market | Asset | APR |
|---|---|---|---|
|  CRV  cvxCRV | CRV | 29.0% |
| CRV sdCRV | CRV | 12.3% |
| CRVcvxCRV | CRV | 8.3% |
| crvUSDWETHCRV | TRICRYPTO | 5.5% |
|  GHOcbBTCWETH | TRICRYPTO | 4.9% |
| crvUSD ZCHF | FOREX | 4.4% |
|  USDCWBTCWETH | TRICRYPTO | 3.0% |
CRV, currency and mixed-asset pools carry different price exposures. Their APRs should not be read as interchangeable alternatives to USD yields.
Protocol activity and stability
The Thursday-noon balances and completed-week activity were mixed: borrowing and indexed trading volume fell, while indexed DEX fees increased. Mint-market debt has since rebounded. Read the peg, debt and liquidity figures together; fee growth alone does not establish market safety.
crvUSD & scrvUSD
| Metric | Value | Weekly change |
|---|---|---|
| Mint-market debt | $73.3M | -3.3% |
 scrvUSD yield (APY) | 3.3% | +1.2 pp |
| scrvUSD assets / mint debt | 21.6% | +0.5 pp |
| crvUSD oracle price | $0.9998 | -$0.0001 |
| Average borrow APY | 3.6% | +1.0 pp |
| PegKeeper debt | 7.83M crvUSD | -7.98M crvUSD |
| Mint borrowing fees collected | $43.5k | +42.9% |
Weekly changes are recomputed from matched historical observations, not the rounded prior issue. Balance and rate comparisons use Thursday noon UTC; activity covers the seven complete days ending Thursday 00:00 UTC.
PegKeeper debt is crvUSD minted into liquidity pools, not a reserve fund. Average borrow APY is debt-weighted across mint markets; individual market rates differ. For crvUSD holders, Savings crvUSD (scrvUSD) is a separate earning option from lending or providing liquidity.
Llamalend
| Metric | Value | Weekly change |
|---|---|---|
Llamalend TVL | $252M | -2.6% |
Supplied | $94.3M | +0.6% |
Borrowed | $142M | -1.5% |
Collateral | $226M | -3.0% |
Loans | 1,165 | +13 |
V2 accrued admin fees | $1.63k | -0.7% |
Totals include lending and crvUSD mint markets; supplied assets are lending-only. The fee row covers accrued admin fees in v2 markets, not fee collections.
DEX
| Metric | Value | Weekly change |
|---|---|---|
Indexed volume | $674M | -13.1% |
Indexed swaps | 395k | +13.2% |
Indexed trading fees | $156.0k | +11.4% |
DEX activity covers ten indexed chains and excludes YieldBasis. Unindexed-chain activity and unpriced dollar amounts are omitted; these are not all-chain totals. Pool fees are distinct from DAO revenue, crvUSD minting fees and Llamalend fees.
DAO
| Metric | Value | Weekly change |
|---|---|---|
 veCRV distribution | $91.3k | +1.7% |
| veCRV APR | 1.941% | +0.185 pp |
| CRV emissions (weekly gauge allocation) | 1.86M CRV ($586.3k) | -0.004% |
| Annual CRV inflation | 4.017% | -0.003 pp |
Weekly CRV emissions are scheduled gauge allocations, not tokens already claimed. Their weekly change is measured in CRV, not dollars.
Governance and protocol updates
Curve infrastructure is live on Arc
Arc mainnet launched this week with USDC gas fees. Curve's pool and gauge factories are deployed. No pools or gauges had been created through the checked factories, and CRV was not configured in the gauge factory. This expands where pools can be created; it is not yet a live yield opportunity.
TricryptoUSDC aims for higher earnings, not more volume
The analysis behind the update makes a deliberate trade-off: higher fees in exchange for lower volume. In simulations, average swap fees rose from about 0.10% to 0.36% and volume fell about 46%, yet total swap fees more than doubled.
The goal is higher earnings for LPs and the DAO, not more trading activity. The parameters were tested across multiple BTC and ETH volatility scenarios, but the modeled gains are not guaranteed live returns. For traders, the change means higher swap fees once applied.
Vote 1496 has been executed and the pool-parameter ramp is underway. The higher fees still need a separate apply transaction after a three-day delay; traders should check the live fee.
Rewards for veCRV votes
Existing veCRV holders can compare rewards for directing CRV emissions on Votemarket. Two selected campaigns offer weekly reward budgets of 40,000 DOLA for DOLA/sUSDe and 10,000 USDC for OETH/WETH.
These budgets are shared among eligible voters, subject to campaign caps; they are not LP returns. Check the voting deadline, your 10-day vote-change cooldown and claim/bridging costs before reallocating.
Ecosystem news
Metronome reports recovery; its synths remain below par
Metronome says it has closed the backing shortfall behind msUSD and msETH. This is the issuer's account, not an independently verified backing assessment. Metronome also says its internal swap remains closed indefinitely.
At the checked block, selling one msUSD in the Ethereum frxUSD/msUSD pool returned about 0.920 frxUSD; selling one msETH in the msETH/WETH pool returned about 0.896 WETH, before gas. These are small-trade quotes, not prices guaranteed for larger exits. For holders and LPs, the recovery statement should not be treated as a promise of redemption or a return to par.
Risk information: pool risks, lending risks and crvUSD risks.